 By Lina Irawan
Good morning loyal Term Sheet readers, this is energy editor, Jordan Blum, filling in for Allie. The global energy landscape remains profoundly shaped by geopolitical instability, particularly in the Middle East, which continues to be a crucible of chaotic conflict. This persistent turmoil, encompassing regional proxy wars, Houthi attacks on Red Sea shipping, and the broader Israel-Hamas conflict, has consistently injected a significant "fear premium" into global commodity markets. Consequently, fuel and oil prices are still stubbornly sky-high, creating a volatile environment for strategic decision-making in the energy sector.
These myriad geopolitical variables and the resulting commodity price volatility have effectively placed a partial freeze on traditional energy dealmaking, especially within the upstream (exploration and production) and downstream (refining and marketing) sectors. On one side, potential sellers, buoyed by current elevated prices and robust cash flows, often demand inflated valuations for their assets, seeking to capitalize on what they perceive as peak market conditions. On the other side, astute buyers, particularly public companies, tend to adopt a longer-term, more conservative outlook. They scrutinize future price forecasts, consider the potential for economic slowdowns, factor in rising interest rates, and evaluate the increasing capital costs associated with large acquisitions. This fundamental disconnect creates a widening "bid-ask spread," making it exceptionally difficult for buyers and sellers to converge on a mutually agreeable price tag, thereby stifling M&A activity. Furthermore, growing environmental, social, and governance (ESG) pressures from investors and regulators add another layer of complexity, pushing some potential buyers to be more selective about acquiring fossil fuel assets, especially those with high carbon footprints or significant regulatory hurdles.
The main exception to this M&A slowdown, however, is found in the so-called midstream sector. This vital segment of the energy industry encompasses the pipelines, storage facilities, and gathering and processing systems that are essential for moving oil and gas from the wellheads to refineries, power plants, or liquefied natural gas (LNG) export hubs. Unlike upstream producers, whose revenues are directly tied to volatile commodity prices, midstream companies typically operate on a fee-based model, earning revenue for the volume of product transported or stored, regardless of the market price. This inherent stability and predictable cash flow make midstream assets particularly attractive during periods of market uncertainty.
"Midstream has been pretty busy," confirmed Andrew Dittmar, a principal analyst at Enverus Intelligence Research, highlighting the sector’s resilience. "There’s just such a demand for infrastructure right now, particularly on the [natural] gas side, as we sort of reshape the U.S. gas market with LNG demand coming online on the Gulf Coast and data center demand increasing." The United States has rapidly emerged as a dominant force in global LNG exports, driven by Europe’s urgent need for energy security following the conflict in Ukraine, as well as burgeoning demand from Asian markets. This has spurred a massive buildout of liquefaction and export terminals along the U.S. Gulf Coast, such as the Golden Pass, Plaquemines, and Port Arthur LNG projects, all of which require extensive pipeline networks to feed them with natural gas from prolific shale basins. Concurrently, the exponential growth of artificial intelligence (AI) is creating an unprecedented surge in demand for electricity, particularly from energy-intensive data centers. Natural gas, with its reliability and scalability, is often the preferred baseload power source to complement intermittent renewable energy, further fueling the need for robust gas infrastructure.
This upswing in pipeline plays and broader energy infrastructure received a potential boost recently with the Senate introduction of a bipartisan infrastructure permitting reform bill. This legislative effort aims to streamline the complex and often protracted approval processes for major energy projects, a hurdle that has historically delayed both fossil fuel and renewable initiatives. The bill could gain significant legislative momentum before the end of the year, driven by a shared understanding across the political spectrum that efficient infrastructure development is crucial for economic competitiveness and national energy security. Such a law would benefit an "all-of-the-above" energy strategy, directly supporting the burgeoning AI boom. This means expediting not only oil and gas pipelines and related projects but also critical wind farms, solar power installations, and essential electric transmission projects—all of which have faced substantial opposition and delays, particularly during the previous Trump administration and through extensive environmental review processes under the National Environmental Policy Act (NEPA). By accelerating these approvals, the legislation could unlock billions of dollars in infrastructure investment, significantly modernize the nation’s energy grid, and further speed up dealmaking across the entire energy spectrum.
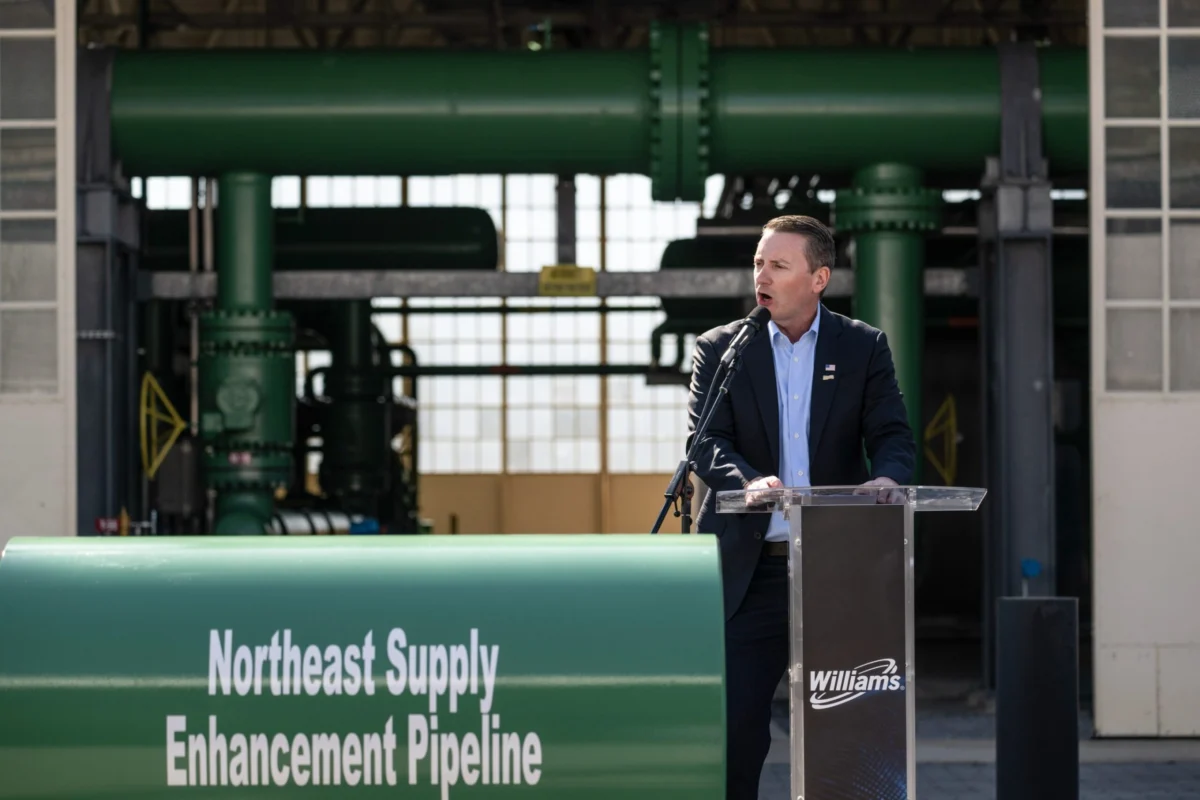
The market has already seen a flurry of significant midstream transactions underscoring this trend. Recently, Tulsa-based ONEOK, a major natural gas liquids (NGL) and natural gas pipeline operator, acquired West Texas’s Brazos Midstream’s Permian Basin assets for a substantial $4.42 billion. This strategic move consolidates ONEOK’s presence in one of the most prolific oil and gas producing regions in the world. This comes shortly after pipeline giant Williams acquired Momentum Midstream and its extensive Texas and Louisiana pipeline gathering and processing facilities for $5.5 billion, enhancing its footprint in key Gulf Coast corridors that link production to refining and crucial LNG export hubs. In another notable deal, Western Midstream paid $1.6 billion for Brazos’s Delaware Basin facilities, targeting the western lobe of the Permian, a highly active sub-basin.
These deals essentially all involve private equity firms selling high to public companies looking to build scale and secure long-term, stable cash flows. Private equity often plays a crucial role in developing and optimizing mid-sized infrastructure assets, taking on initial risks, and then monetizing them when they reach maturity and attract larger, publicly traded entities. "I think the market does favor larger, integrated midstream systems, and we’re going to continue to see some of the smaller players, particularly on the private side, rolled up amid a considerable acquisition appetite from the large companies," Dittmar explained. This consolidation allows for greater operational efficiencies, stronger balance sheets, and better access to capital markets. On the oil side of midstream, pipeline giant Enbridge, a major Canadian energy infrastructure company, just bought Tallgrass Energy’s crude assets for $2.55 billion, expanding its U.S. crude oil footprint. Similarly, Plains All American Pipeline paid $585 million for Silver Creek Midstream in Wyoming, further demonstrating the ongoing demand for crude oil transportation and storage infrastructure.
As for the oil and gas production side of the business—the upstream sector—there hasn’t been a massive deal since early February when Devon Energy paid a staggering $26.5 billion for Coterra Energy. That colossal acquisition, focused on consolidating Devon’s position in the prolific Delaware Basin, notably came weeks before the onset of the current elevated tensions in the Iran-linked conflicts. The timing is crucial; the subsequent geopolitical instability introduced a level of market uncertainty and cost volatility that has largely dampened the appetite for similarly sized upstream mergers. The biggest upstream deal since then has been Magnolia Oil & Gas paying $4 billion for Warburg Pincus’s and Kayne Anderson’s WildFire Energy assets in South Texas’s Eagle Ford Shale. While significant, these companies are not exactly household names, reflecting a shift towards more targeted, regional consolidations rather than mega-mergers involving industry titans.
Now, Devon Energy is itself trying to sell its own Eagle Ford assets, a strategic move to help cut down on the substantial debt it assumed from the Coterra deal. This divestiture signals a focus on core assets and balance sheet optimization in a challenging market. Interestingly, global energy major BP was closely eyeing those assets but reportedly backed off. Dittmar noted that BP’s initial interest in expanding its U.S. shale portfolio is highly significant. European majors, often under intense pressure to divest fossil fuel assets and pivot towards renewable energy, rarely show such overt interest in U.S. onshore plays. "If you have a global major looking at U.S. onshore assets, it continues to speak to how competitive and attractive the opportunities are here, even as we talk about inventory scarcity," he said. This points to the enduring profitability and technological advantages of U.S. shale, making proven, existing assets highly valuable as prime drilling locations become more finite.
This dynamic is further complicated by intriguing cross-border capital flows. Major U.S. companies are increasingly looking to explore internationally again, as the domestic U.S. shale business matures and the quest for new, large-scale discoveries moves beyond established basins. This outward gaze seeks diversification and potentially higher returns in frontier regions. Simultaneously, more international players are willing to pay a premium for U.S. assets to ensure long-term energy supplies, especially for LNG. For nations like Japan, securing stable access to U.S. natural gas through direct asset ownership (as seen with Mitsubishi’s acquisition of gas fields) is a critical component of their national energy security strategy. "It’s interesting that we talk about international capital coming to the U.S. at the same time that U.S. capital is looking to go abroad," Dittmar added, highlighting a fascinating arbitrage in global energy investment as different regions seek to optimize their portfolios amidst shifting geopolitical and economic landscapes.
Jordan Blum
[email protected]
@jdblum23
Submit a deal for the Term Sheet newsletter here.
Joey Abrams curated the deals section of today’s newsletter. Subscribe here.
VENTURE CAPITAL
The burgeoning AI revolution continues to be a magnet for venture capital, with significant investments pouring into infrastructure, hardware, and software solutions designed to power this transformative technology. The following deals highlight the diverse areas attracting capital:
- GMI Cloud, a Mountain View, Calif.-based cloud-computing provider offering GPU infrastructure for AI workloads, raised $223 million in Series B funding. ARCHIV led the round and was joined by NVIDIA, underscoring the critical need for scalable computational power to support AI development.
- CScale, a Palo Alto, Calif.-based developer of optical interconnect technology for AI data centers, raised $145 million in Series C funding. Atreides Management, Valor Equity Partners, and Premji Invest led the round, reflecting the immense demand for faster, more efficient data transfer within the sprawling data centers that house AI operations.
- Hertha Metals, a Conroe, Texas-based producer of high-purity iron and steel for rare-earth magnets, raised $133.7 million in Series A funding. Khosla Ventures and Doerr Capital led the round and were joined by Gates Frontier, Toyota Ventures, and Siemens Financial Services, indicating a strategic focus on the foundational materials necessary for advanced AI hardware and renewable energy technologies.
- Flow Engineering, a San Francisco-based software platform that helps hardware teams manage requirements, design changes, and testing, raised $50 million in Series B funding. Antonio Gracias and Gavin Baker led the round and were joined by Human Capital, Evantic, SV Angel, Odyssey, EQ, and others, emphasizing the need for robust software tools to accelerate complex hardware development cycles.
- Miter, a San Francisco-based AI-powered workforce-management platform for construction companies, raised $40 million in Series B funding. Battery Ventures led the round and was joined by Bessemer Venture Partners and Coatue, showcasing AI’s growing application in optimizing labor and project management in traditional industries.
- Relay, a Raleigh, N.C.-based communications and workflow platform for frontline workers, raised $36 million in funding. International Paper led the round, demonstrating the push to enhance efficiency and connectivity for essential workers across various sectors.
- Inbolt, a Paris, France-based developer of AI-powered 3D-vision software for industrial robots, raised $12.5 million in funding. Shift4Good led the round and was joined by Bridges Climate Transition Partners and others, highlighting the advancements in robotic automation driven by sophisticated AI vision systems.
- Rig Security, a Tel Aviv, Israel-based cybersecurity platform that monitors and controls AI agents’ access to corporate systems, raised $12 million in seed funding. Ten Eleven Ventures and Brightmind Partners led the round and were joined by CrowdStrike Falcon Fund, addressing the critical need for security protocols as AI becomes more integrated into enterprise operations.
- Kanu AI, a Seattle, Wash.-based AI platform that turns employee workflows into custom business software, raised $11.7 million in funding. Trilogy Equity Partners led the round and was joined by a16z speedrun, BMW i Ventures, and Accel, focusing on leveraging AI to streamline and customize internal business processes.
- Hop Aero, an Orange, Calif.-based developer of autonomous hypersonic cargo rockets for military logistics, raised $11 million in funding. Initialized Capital led the round and was joined by Y Combinator, Lunar Ventures, System.One, and Outsized Ventures, pointing to innovation in defense and logistics technologies with high-speed autonomous capabilities.
- Osavul, a Luxembourg-based cyber-threat intelligence company, raised €8.5 million ($10 million) in Series A funding. 33N Ventures led the round and was joined by Balnord, G+D Ventures, and existing investor 42CAP, underscoring the growing investment in advanced cybersecurity solutions.
- Beltic, a San Francisco-based agent verification infrastructure company, raised $8.8 across seed and pre-seed rounds. Norwest led the seed round and was joined by Restive Ventures, Oxford Seed Fund, and Collide Capital, focusing on building trust and security in digital interactions.
- Destro AI, a Brooklyn, N.Y.-based AI software provider for warehouse robots, raised $8 million in seed funding. Base10 Partners and Bonfire Ventures led the round and was joined by CoFound Partners, indicating continued automation and efficiency drives within the logistics sector.
- Quotr, a San Francisco-based AI-powered construction estimating and procurement platform, raised $4 million in seed funding. Llama Ventures led the round and was joined by angel investors, further demonstrating AI’s disruptive potential in construction planning and cost management.
PRIVATE EQUITY
- Nuveen acquired Schroders, a London, U.K.-based asset manager, for £9.9 billion ($13.3 billion), signifying a major consolidation in the global asset management industry.
- Aspirity Partners agreed to acquire a majority stake in Onomondo, a Copenhagen, Denmark-based provider of cellular connectivity for internet-connected devices, in a combined investment worth more than €100 million ($113 million), highlighting the continued growth in IoT and connected device infrastructure.
- Sovos, backed by Hg, acquired Flowie, a Paris, France-based AI-powered platform for finance workflows, and Blue dot, a Tel Aviv, Israel-based platform that helps companies identify and recover VAT overpayments. Financial terms were not disclosed, showcasing the strategic acquisitions aimed at enhancing financial compliance and efficiency through AI.
- TRG, a portfolio company of Gemspring Capital, acquired Fentron, a Westerville, Ohio-based cybersecurity consulting firm. Financial terms were not disclosed, reflecting the ongoing demand for specialized cybersecurity services across industries.
EXITS
- Capitolis agreed to acquire eSecLending, a Boston, Mass.-based securities lending business, from Parthenon Capital in a transaction valued at $200 million, indicating a strategic move in the financial services sector to expand offerings.
FUNDS + FUNDS OF FUNDS
- Stride Consumer Partners, a Boston, Mass.-based growth equity firm, raised $550 million for its second fund focused on consumer products and services companies, signaling continued investor confidence in the consumer sector.
PEOPLE
- Azarias Capital Management, a Berwyn, Pa.-based private investment firm, promoted Jocelyn Dalkin to Partner, recognizing her contributions to the firm’s growth and investment strategies.
