
 By admin
American Airlines, currently holding its position as the world’s largest carrier by fleet size and scheduled passengers carried, has long maintained a robust ecosystem of credit card partnerships to incentivize brand loyalty. Among its most prestigious financial products is the Citi® / AAdvantage® Executive World Elite Mastercard®, a premium travel tool designed specifically for high-frequency flyers who prioritize lounge access and elite status qualification. As of September 2026, the landscape for travel rewards has become increasingly competitive, leading to the launch of a record-breaking welcome incentive: new cardholders can now earn a staggering 125,000 AAdvantage bonus miles after spending $15,000 on purchases within the first five months of account opening. This offer represents the highest public bonus ever recorded for this specific card, providing a unique window of opportunity for travelers to significantly bolster their mileage balances.
To understand the sheer scale of this offer, one must look at the current valuation of the AAdvantage currency. Based on industry benchmarks for late 2026, AAdvantage miles are valued at approximately 1.45 cents each, making the 125,000-mile bonus worth an estimated $1,813. Unlike some other domestic carriers that have moved toward more aggressive dynamic pricing models, American Airlines has retained several high-value "sweet spots" within its redemption charts, particularly when booking travel on Oneworld partner airlines such as Qatar Airways, British Airways, and Japan Airlines. For many, a bonus of this magnitude is sufficient to cover a round-trip business class ticket to Europe or a significant portion of a luxury itinerary to Asia or the South Pacific. However, the $15,000 spending requirement is a substantial hurdle, necessitating a clear strategy for potential applicants.

Before initiating an application for a card with such a high barrier to entry, it is critical to navigate the complex web of eligibility requirements imposed by Citibank. The most significant restriction is the "48-month rule," a policy Citi uses to prevent "churning"—the practice of repeatedly opening and closing accounts solely to harvest welcome bonuses. According to the current terms, the welcome bonus is not available to any applicant who has received a new account bonus for a Citi / AAdvantage Executive account in the previous 48 months. Crucially, the 48-month "clock" does not start when you open the card or when you close it; it begins on the date the previous bonus actually posted to your account. For those who have held the card in the past, verifying this exact date is a vital first step. This can typically be accomplished by reviewing old billing statements or contacting Citi’s customer service directly at 888-766-2484.
Furthermore, eligibility is restricted for those who have recently engaged in "product changes." If you converted a different Citi credit card—such as a Citi Strata Premier or a Citi Double Cash—into an AAdvantage Executive card within the last 48 months and that original card had earned a bonus, you may be disqualified from the current offer. Additionally, the offer is strictly limited to residents of the United States and its territories, though it specifically excludes residents of Puerto Rico and the U.S. Virgin Islands. For those who currently hold other American Airlines cobranded cards, such as the Citi / AAdvantage Platinum Select or the Barclays AAdvantage Aviator Red, there is good news: holding these cards generally does not disqualify you from the Executive card bonus, provided you meet the specific 48-month criteria for the Executive product itself.
Beyond the bonus-specific rules, applicants must also adhere to Citi’s general credit application frequency limits. Known in the credit card community as the "1/8 and 2/65" rules, these guidelines dictate that a consumer can only apply for one Citi card (personal or business) every eight days and no more than two cards in any 65-day rolling window. Applying more frequently than this almost guarantees an automatic rejection, regardless of the applicant’s credit score. Speaking of credit scores, the Citi / AAdvantage Executive is a premium "World Elite" Mastercard, typically requiring a "Good" to "Excellent" credit profile. While some data points suggest approvals for those with scores in the high 600s, a FICO score of 720 or higher is generally recommended to ensure a smooth approval process and a credit limit high enough to accommodate the $15,000 spending requirement.

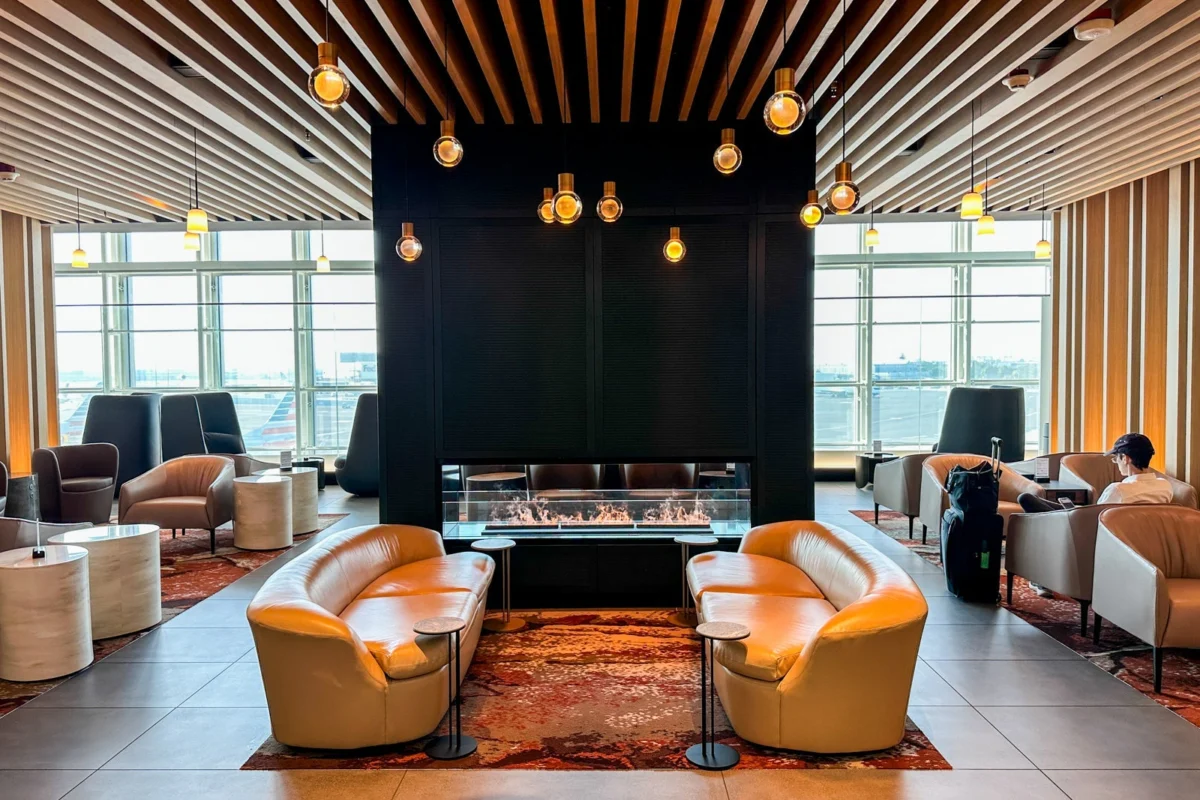
The primary allure of the Citi / AAdvantage Executive card, beyond the massive influx of miles, is its suite of luxury travel benefits, most notably the full Admirals Club membership. While many credit cards offer limited lounge passes or "access" that still requires a fee, the Executive card provides a primary membership that allows the cardholder and up to two guests (or immediate family) entry into nearly 50 Admirals Club locations worldwide. In an era where airport terminals are increasingly crowded, this benefit provides a sanctuary of productivity and relaxation. Furthermore, the card allows for the addition of authorized users for a fee, and these authorized users also receive their own Admirals Club access (though not a full membership), making it a powerful tool for families or business partners who travel frequently.
In addition to lounge access, the card serves as a catalyst for attaining AAdvantage elite status. Under American Airlines’ Loyalty Points system, every eligible dollar spent on the card earns 1 Loyalty Point toward status, in addition to the redeemable miles. The Executive card often features additional "boosters," such as a 10,000 Loyalty Point bonus after reaching a certain spending threshold in a qualification year. For those aiming for Gold, Platinum, or the coveted Executive Platinum status, the spending required to hit the 125,000-mile bonus will simultaneously propel the cardholder toward higher tiers of status, which come with perks like complimentary upgrades, priority baggage handling, and expanded award availability.
Prospective applicants should also consider the financial implications of the card’s annual fee, which sits at the higher end of the market. To justify this cost, one must utilize the ancillary credits provided. The card typically includes a statement credit for Global Entry or TSA PreCheck application fees every four years, as well as various monthly credits for services like Grubhub or Lyft, and a recurring credit for Avis or Budget car rentals. When maximized, these credits can offset a significant portion of the annual fee, effectively lowering the "cost" of the 125,000-mile bonus.
If an application is not immediately approved, it does not necessarily mean the end of the road. Citi maintains a reconsideration line (800-695-5171) where applicants can speak with a credit analyst. Common reasons for a "pending" or "denied" status include a high debt-to-income ratio or a high total credit limit across existing Citi cards. In the latter case, an applicant can often secure an approval by offering to move a portion of their credit limit from an existing card—like a Citi Custom Cash—to the new AAdvantage Executive card. This demonstrates to the bank that you are not seeking "new" credit, but rather reorganizing your existing credit line to better suit your current travel needs.
As the travel industry continues to evolve in 2026, the value of direct airline partnerships remains high. American Airlines has invested heavily in its "Flagship" premium experiences and its partnership with the Oneworld alliance, making AAdvantage miles a versatile tool for global exploration. Whether you are looking to book a "sweet spot" award like a 70,000-mile business class seat on Qatar Airways’ Qsuite or simply want to ensure your family can wait for their flight in the comfort of a lounge, the Citi / AAdvantage Executive card is a central pillar of that strategy.
In conclusion, the current 125,000-mile offer is a landmark event in the world of travel rewards. While the $15,000 spending requirement over five months is significant, the combination of the mile valuation, the Admirals Club membership, and the acceleration toward elite status creates a compelling value proposition. By carefully checking the 48-month eligibility rule, monitoring application frequency, and preparing for the minimum spend, savvy travelers can leverage this offer to unlock thousands of dollars in future travel value. As always, the key to success with premium credit cards lies in disciplined spending and a thorough understanding of the underlying terms and conditions, ensuring that the rewards earned far outweigh the costs of the card’s maintenance.
