 By Lina Irawan
At the heart of the dispute is Mayor Mamdani’s ambitious pied-à-terre tax, a levy targeting non-primary residences valued at $5 million or more, designed to generate substantial revenue for New York City and address issues of wealth inequality. Introduced as a cornerstone of Mamdani’s progressive agenda, the tax aims to ensure that the city’s wealthiest residents, particularly those who own luxury second homes, contribute a "fair share" to public services and affordable housing initiatives. Proponents argue that such taxes are vital for funding critical infrastructure and social programs, especially in a city grappling with persistent housing crises and widening economic disparities. Critics, however, often voice concerns about potential capital flight, the administrative burden on property owners, and the broader impact on the luxury real estate market.
The Appellate Division’s four-judge panel acted swiftly, hearing arguments just a week prior to delivering its decisive reversal of a September 29 judgment by Staten Island Supreme Court Justice Wayne Ozzi. Justice Ozzi had previously granted the homeowners both injunctive and declaratory relief, effectively pausing the tax rollout. The unanimous nature of the appellate panel’s decision underscores a clear legal consensus on the matter of standing, signaling a strong message regarding the thresholds for challenging governmental actions in New York State courts. This swift and unified ruling effectively denied the homeowners’ petition and dismissed the case, allowing the city to proceed with its tax collection efforts.
The lawsuit originated in August when a group of seven homeowners, represented by the high-profile former First Deputy Mayor Randy Mastro, filed a complaint against the city. Mastro, a prominent attorney known for his tenacious legal challenges against municipal policies, particularly those implemented by progressive administrations, spearheaded the effort to halt the tax. The homeowners’ primary grievance centered on the Department of Finance’s (DOF) publication of a supplemental roll encompassing approximately 900,000 properties and the subsequent mailing of roughly 17,000 notices to owners who might be subject to the surcharge. They argued that the city had placed an undue burden on property owners by requiring them to actively prove their primary residency, rather than first leveraging its own extensive records to identify potential non-primary residences. This, they contended, represented a flawed and overly broad approach to tax implementation, creating unnecessary anxiety and administrative hassle for thousands of New Yorkers.
However, the appellate court sidestepped the merits of this specific administrative argument, choosing instead to focus on the fundamental legal principle of "standing." Standing, in legal parlance, refers to the capacity of a party to bring a lawsuit in court. To have standing, a plaintiff must demonstrate a "concrete and particularized injury" that is "actual or imminent," "fairly traceable" to the defendant’s actions, and "redressable" by a favorable court decision. In this case, the court found that the homeowners had not adequately shown such a concrete injury.
The judges articulated that merely appearing on the DOF’s supplemental roll or receiving an informational notice was insufficient to establish standing. They reasoned that the notice "serves an informational purpose," akin to a preliminary debt collection letter, designed to alert potential taxpayers rather than impose an immediate, undeniable liability. Furthermore, the court acknowledged that the state legislature, in crafting the tax law, "must have anticipated that the list of notice recipients would not be exact or flawless." This anticipation, the judges suggested, was precisely why an exemption process was built into the legislation, providing a mechanism for property owners to challenge their inclusion and prove their primary residency without resorting to litigation.
The court further dismissed the homeowners’ claims of harm stemming from "rollout confusion," characterizing such inconveniences as too "generalized, tenuous, and ephemeral" to constitute a legal injury. The plaintiffs had failed to present any evidence that the published information had been misused, or that they faced specific threats such as stalking or fraud directly attributable to the city’s actions. The judges also pointed out that much of the information deemed sensitive by the homeowners, such as owner names, assessed values, and market values, is already publicly available through the city’s annual assessment rolls. This pre-existing public accessibility further undermined claims of unique harm related to data exposure.
Moreover, the court deemed the cost and effort associated with applying for an exemption insufficient grounds for injury. It highlighted that all taxpayers are expected to incur some level of time and expense in complying with tax rules and regulations. Crucially, the homeowners had failed to adequately document or quantify the specific costs they allegedly incurred in navigating the exemption process, leaving the court without concrete evidence of financial injury. This emphasis on documented and quantified harm is a standard requirement in legal challenges seeking relief based on economic injury.
The individual circumstances of the petitioners also weakened their collective standing. Court documents revealed that two of the seven petitioners, Rachel O’Brien and Carmine Morano, never even alleged that they received a notice from the DOF. The remaining five petitioners, perhaps anticipating the legal battle or simply complying with the city’s administrative process, had successfully secured exemptions after the lawsuit was filed, effectively removing them from the pool of potentially affected taxpayers. This fact likely played a significant role in the court’s assessment that the plaintiffs could not demonstrate ongoing or imminent harm.
While ultimately dismissing the case, the appellate panel did side with the homeowners on two procedural points. It rejected the city’s argument that the granting of exemptions to the petitioners rendered the case moot, acknowledging that the underlying legal question regarding the tax’s rollout procedure remained relevant. The court also rebuffed the city’s contention that challenges to the tax law were limited exclusively to appeals before the city’s Tax Commission, indicating that judicial review was indeed permissible under certain circumstances, even if not met in this specific instance. Furthermore, the court strategically declined to issue a ruling on whether the DOF had violated its own rules by not relying on 2024 income-tax data when selecting recipients for the notices, thereby avoiding a potentially complex administrative law question.
This ruling, while a clear win for Mayor Mamdani, does not fully resolve all legal challenges confronting the pied-à-terre tax. Reports from outlets like Gothamist indicate that the surcharge faces at least three other separate legal battles, suggesting that the city’s journey to fully implement and collect this tax may still encounter further hurdles. These ongoing challenges could potentially delve into constitutional questions regarding the tax itself, or challenge other aspects of its implementation that were not addressed by the "standing" argument in this particular case.
In response to initial administrative complexities, the city has already demonstrated a willingness to adapt its approach. Following the state’s transmission of early 2025 income-tax data on August 12, the Department of Finance proactively cleared 1,210 owners from the initial list and announced plans to send updated letters to approximately 10,800 others. This course correction, aimed at refining the targeting of the tax, suggests the city is keen to minimize inaccuracies and streamline the process. Gothamist further reported that the DOF has since granted more than 8,800 exemption requests, indicating a robust administrative mechanism for addressing individual cases.
The projected revenue figures for the tax have varied, reflecting the inherent complexities of estimating collection from a novel levy. Comptroller Mark Levine had earlier estimated that the tax could generate up to $380 million annually from approximately 11,200 properties. Mayor Mamdani, however, has consistently maintained a more optimistic projection, asserting that the tax will raise $500 million each year. This discrepancy highlights the fluid nature of revenue forecasting for new tax instruments, influenced by factors such as compliance rates, the number of successful exemptions, and the precise valuation of luxury properties. The actual collection figures will be closely watched as a benchmark for the tax’s effectiveness and the city’s fiscal health.
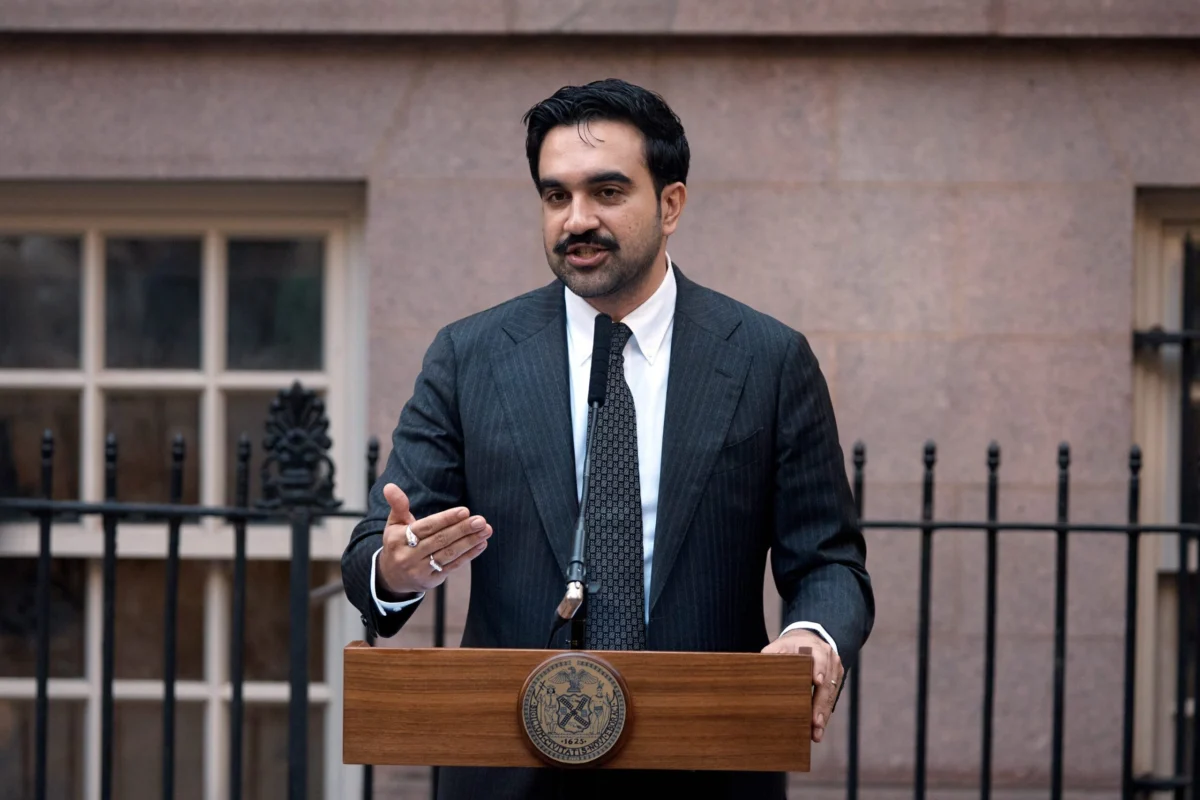
Mayor Mamdani wasted no time in celebrating the appellate court’s decision, issuing a statement that underscored his administration’s commitment to progressive taxation. He declared that the court "rejected an attempt by the ultrawealthy to avoid paying their fair share," framing the ruling as a victory for equity and social responsibility. Mamdani reiterated his philosophy that "owning a second home worth over $5 million should come with a responsibility to the city that makes it valuable," echoing a sentiment often heard from proponents of wealth redistribution.
Looking ahead, the Mayor affirmed the city’s resolve to continue defending the law against "ongoing challenges in Suffolk County," explicitly calling out "some of the same uberwealthy interests whose arguments just lost in court today." This statement signals that the political and legal battle over the pied-à-terre tax is far from over, with Mamdani positioning his administration against powerful, well-resourced opponents. He concluded with a promise to "implement the pied-a-terre surcharge fairly and efficiently, ensuring that those most able to contribute do their part to build a city that works for everyone."
This ruling represents a crucial step forward for New York City’s pied-à-terre tax, solidifying its legal footing against initial procedural challenges. By affirming the city’s right to implement the tax without immediate judicial interference, the Appellate Division has empowered Mayor Mamdani’s administration to pursue its fiscal and social policy objectives. While further legal skirmishes are anticipated, this decision removes a significant immediate obstacle, allowing the city to move closer to realizing the projected revenue from this landmark luxury tax. The outcome will undoubtedly influence future discussions on wealth taxation and social equity in New York and potentially serve as a precedent for other major urban centers grappling with similar economic disparities.
